In This Series
In This Guide
Key Takeaways
- Inflation silently reduces the buying power of your retirement income over time.
- Traditional fixed withdrawals may not keep pace with rising costs of living.
- Structured income strategies can sometimes incorporate features designed to combat inflation.
- Proactive planning for inflation is essential to maintain your lifestyle throughout retirement.
Angle: How inflation erodes traditional withdrawals and how an income-focused strategy might help maintain purchasing power.
The Erosion of Fixed Income: A Real-Life Impact
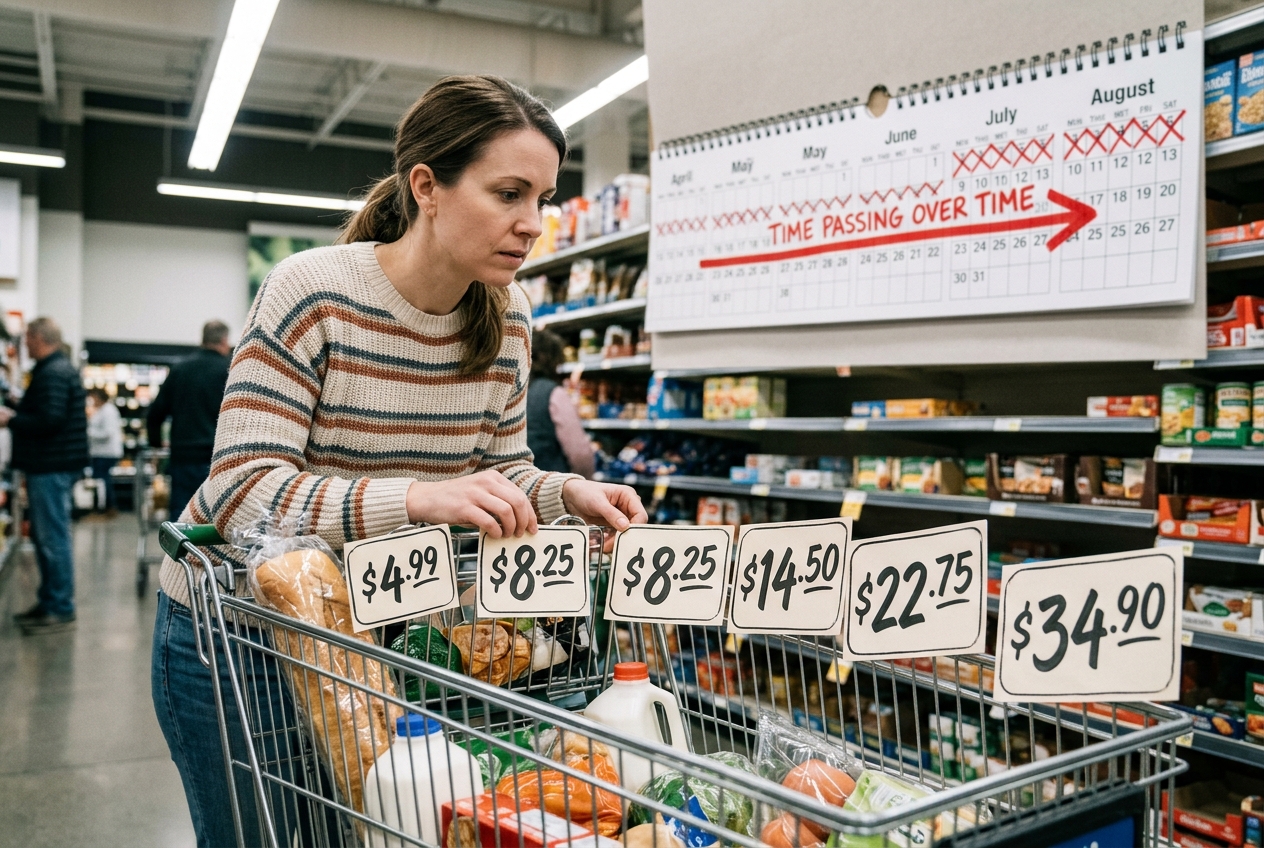
Imagine your monthly income is $4,000. If inflation runs at 3% per year, in just ten years, that same $4,000 will only buy what approximately $2,976 bought today. This means essential goods and services become incrementally more expensive each year, squeezing your budget without your income actually decreasing in dollar amount. This often leads to a different way of thinking about how your income needs to adapt over time. This isn't just about big purchases; it affects everything from groceries and utilities to healthcare costs. For many retirees, this slow, steady erosion of purchasing power is a major source of financial stress, even if their nominal income appears stable.
Why Traditional Strategies Fall Short Against Rising Costs
Many traditional retirement withdrawal strategies, like the 4% rule, often struggle to adequately address inflation. While some models suggest adjusting withdrawals for inflation, doing so can put additional strain on a portfolio already vulnerable to market downturns. If your portfolio is declining while you're also increasing your withdrawals to keep pace with inflation, you compound the risk of running out of money. This is where many people begin to question if a purely market-dependent approach can truly provide long-term income security. It highlights the importance of having a portion of your income strategy designed to either keep pace with or be insulated from the effects of rising prices.
Seeking Inflation Protection in Your Income Plan
An income-first approach, particularly through certain structured income strategies, can sometimes incorporate features designed to offer a degree of inflation protection. While no solution is perfect, some options aim to provide income that increases over time or is designed to maintain its purchasing power. This offers a different layer of security than simply relying on market growth to offset inflation. For some households, this changes the conversation from 'How much money do I have?' to 'How much *real* purchasing power will my income provide throughout my entire retirement?' It’s about building a plan that protects not just the dollar amount, but the actual value of your monthly paycheck.
Related Articles
- Turn Savings Into Retirement Paycheck: Avoid Market Risk & Secure Income
- The Longevity Question: Outliving Your Savings in Retirement
- Beyond the 4% Rule: Rethinking Retirement Withdrawal Strategies
- IULs vs Fixed Indexed Annuities for retirement income: How to Compare the Two
- The 4% Rule Is Failing Retirees: Modern Alternatives for Retirement Income
- 7 Retirement Risks That Could Derail Your Retirement Plan
About the Author
John P. Sansaricq is a licensed insurance professional focused on retirement income planning, life insurance strategies, and educational resources for pre-retirees and retirees.
He helps individuals and families explore ways to protect savings, manage risk, and prepare for more informed retirement planning conversations.
See What This Looks Like For You
Reading about retirement strategies is helpful… but the real clarity comes from seeing how this applies to your own numbers.
This guide is designed to help you start thinking differently — the next step is simply understanding what your situation might actually look like.