In This Series
In This Guide
- The Problem: Social Security Alone Isn't Your Full Retirement Paycheck
- The Gap: Understanding Your Retirement Income Shortfall
- Why Traditional Savings Fall Short: Accumulation vs. Income
- The Hidden Risks to Your Retirement Paycheck: Market Volatility and Sequence of Returns
- Shifting Your Mindset: From Savings to Structured Income
- Exploring Strategies to Create Your Own Paycheck
- A Real-Life Income Bridge: Filling the Gap
- Your Next Step: Quantifying Your Income Needs
Key Takeaways
- Social Security typically covers only a fraction of a retiree's income needs, creating a significant 'income gap'.
- Traditional savings like 401(k)s are designed for accumulation, not for automatically generating consistent retirement paychecks.
- Market volatility and unplanned withdrawals pose substantial risks to your retirement income strategy.
- Structured income strategies can help convert your accumulated savings into predictable, reliable monthly income.
- Proactive income planning is essential to bridge the gap and protect your desired retirement lifestyle.
The Gap: Understanding Your Retirement Income Shortfall
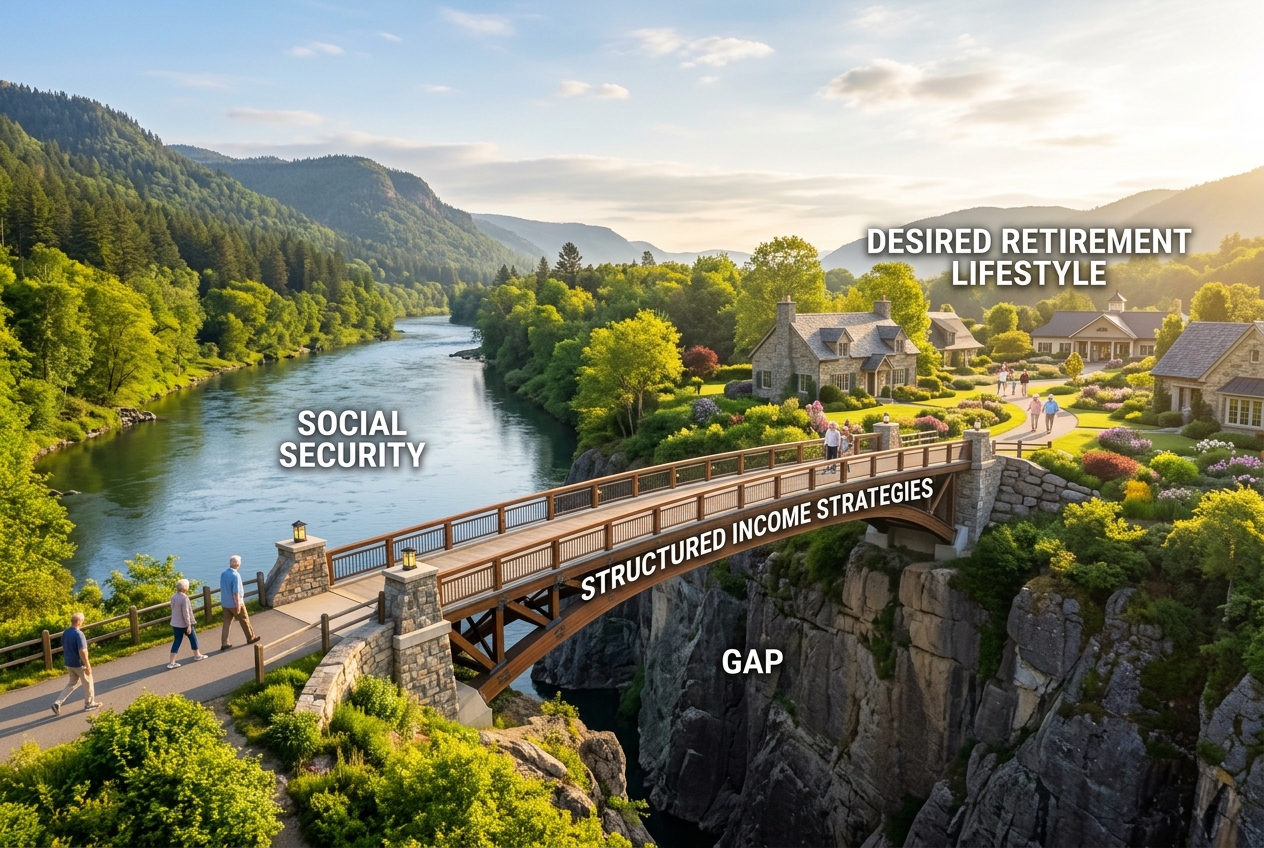
The 'retirement income gap' is simply the difference between the monthly income you actually need to live your desired retirement lifestyle and the predictable income you can expect from sources like Social Security and pensions. It's often larger than people anticipate because it includes not just basic living expenses but also discretionary spending, travel, hobbies, and healthcare costs. For some households, realizing this gap changes the conversation from how much they have saved, to how much reliable income they can actually create each month to bridge that divide.
Why Traditional Savings Fall Short: Accumulation vs. Income
Your 401(k), IRA, and other investment accounts were primarily designed for accumulation – to grow your money over your working years. They are not inherently structured to generate a predictable monthly paycheck in retirement. When you retire, you transition from contributing to withdrawing. This shift requires a different strategy. On paper, a $1 million 401(k) may seem like a large sum. But if you're trying to draw $4,000 a month from it while navigating market fluctuations, it changes how long that $1 million actually lasts, and how much stress it causes you.
Shifting Your Mindset: From Savings to Structured Income
Instead of simply withdrawing from your savings, a structured income approach focuses on converting a portion of your assets into a reliable, often guaranteed, income stream. This is a fundamental shift from an 'accumulation' mindset to an 'income distribution' mindset. It's about designing your finances to deliver a consistent 'paycheck,' much like you received during your working years. This often leads to a different way of thinking about how your money works for you in retirement, prioritizing stability over pure growth for a portion of your funds.
Exploring Strategies to Create Your Own Paycheck
To bridge the retirement income gap and create a more predictable income, many people begin to explore structured income strategies. These approaches are designed to provide income, reduce market dependency, and offer a level of predictability that traditional investment portfolios may not. For instance, some strategies, such as Fixed Indexed Annuities (FIAs) with income riders or certain Indexed Universal Life (IUL) policies, are designed to convert a portion of your savings into a dependable monthly income stream for life, or for a specified period. They aim to provide a 'personal pension' that can complement Social Security and cover essential expenses, helping to create a more resilient retirement income plan.
A Real-Life Income Bridge: Filling the Gap
Consider Jane, who needs $5,000 per month but expects only $2,200 from Social Security. Her income gap is $2,800 monthly. Instead of just pulling this from her $800,000 401(k) and hoping for good market years, she could allocate a portion of her savings, say $300,000, into a structured income strategy. This strategy might then be designed to provide her with a guaranteed $2,000 per month for life, covering a significant portion of her gap. This leaves her with a smaller, more manageable gap of $800, and the remaining $500,000 in her 401(k) can be managed with less pressure, allowing for growth or discretionary spending, knowing her core income needs are largely met. This helps simplify her financial life and reduces uncertainty.
Your Next Step: Quantifying Your Income Needs
Understanding your personal retirement income gap is the first step toward a more secure future. It's about looking beyond the lump sum in your accounts and focusing on the monthly income that sum needs to generate. This is where many people begin to question whether their current plan truly addresses their long-term income needs. Taking the time to quantify your income requirements and explore how your assets can be repositioned to create that stable income can transform your retirement outlook.
Frequently Asked Questions
How much Social Security can I really expect to receive?
The amount you receive from Social Security depends on your earnings history and when you claim benefits. The average monthly benefit for a retired worker is currently around $1,900. However, this is just an average. You can get an estimate of your specific benefit by creating an account on the Social Security Administration's website and viewing your personalized statement.
Is it safe to rely on my 401(k) or IRA for all my retirement income?
While your 401(k) or IRA holds your retirement savings, relying solely on direct withdrawals from these accounts for all your income can expose you to significant market risk, particularly 'sequence of returns risk.' If the market drops early in your retirement, your withdrawals can deplete your principal faster, making it harder for your portfolio to recover. Many people find it beneficial to convert a portion of these savings into more stable, predictable income streams to cover essential expenses.
What's the biggest mistake people make when planning retirement income?
One of the biggest mistakes is failing to shift from an 'accumulation' mindset to an 'income distribution' mindset. People often focus on growing their nest egg but don't have a clear strategy for how that money will consistently generate a monthly paycheck in retirement. This leads to an 'income gap' between Social Security and their desired lifestyle, and an over-reliance on volatile market performance for their daily needs.
How do I know if I have an 'income gap'?
You can identify your income gap by first calculating your estimated monthly expenses and desired discretionary spending in retirement. Then, subtract your predictable income sources, such as Social Security and any pensions. The remaining amount is your income gap. For example, if you need $6,000 per month but only expect $2,500 from Social Security, your income gap is $3,500 per month.
Are these 'structured income strategies' risky?
Structured income strategies, like certain Fixed Indexed Annuities or Indexed Universal Life policies, are designed to provide predictability and often guarantees on income, which can reduce market risk for a portion of your retirement funds. However, like any financial product, they have their own features, benefits, and potential limitations. It's important to understand how they work, their costs, and how they fit into your overall financial plan. They are not 'risk-free' in the sense of all financial products, but they aim to provide a different risk profile for income generation compared to direct market investments.
Related Articles in This Series
- The 401(k) Paradox: Why Growth Doesn't Automatically Mean Retirement Income
- Beyond Today's Dollar: How Inflation and Longevity Threaten Your Retirement Income
- The Appeal of Predictability: Why Stable Income Matters More Than Ever in Retirement
- Tired Landlord Retirement Income Alternatives: How to Turn Rentals Into Predictable Retirement Cash Flow
- Indexed Universal Life for Retirement Income: Beyond the Obvious
- How Inflation Quietly Destroys Retirement Income: What Retirees Need to Know
About the Author
John P. Sansaricq is a licensed insurance professional focused on retirement income planning, life insurance strategies, and educational resources for pre-retirees and retirees.
He helps individuals and families explore ways to protect savings, manage risk, and prepare for more informed retirement planning conversations.
See What This Looks Like For You
Reading about retirement strategies is helpful… but the real clarity comes from seeing how this applies to your own numbers.
This guide is designed to help you start thinking differently — the next step is simply understanding what your situation might actually look like.