In This Series
In This Guide
Key Takeaways
- Sequence of returns risk highlights the danger of poor market performance early in retirement.
- Withdrawing from a declining $500K portfolio amplifies losses and reduces recovery potential.
- The order of returns, not just the average, dictates how long your retirement income will last.
- A 20% market drop in year one is far more damaging than the same drop in year fifteen.
- Understanding this risk is crucial for designing a resilient retirement income strategy.
Angle: timing decisions
The Unseen Threat: How Sequence of Returns Works
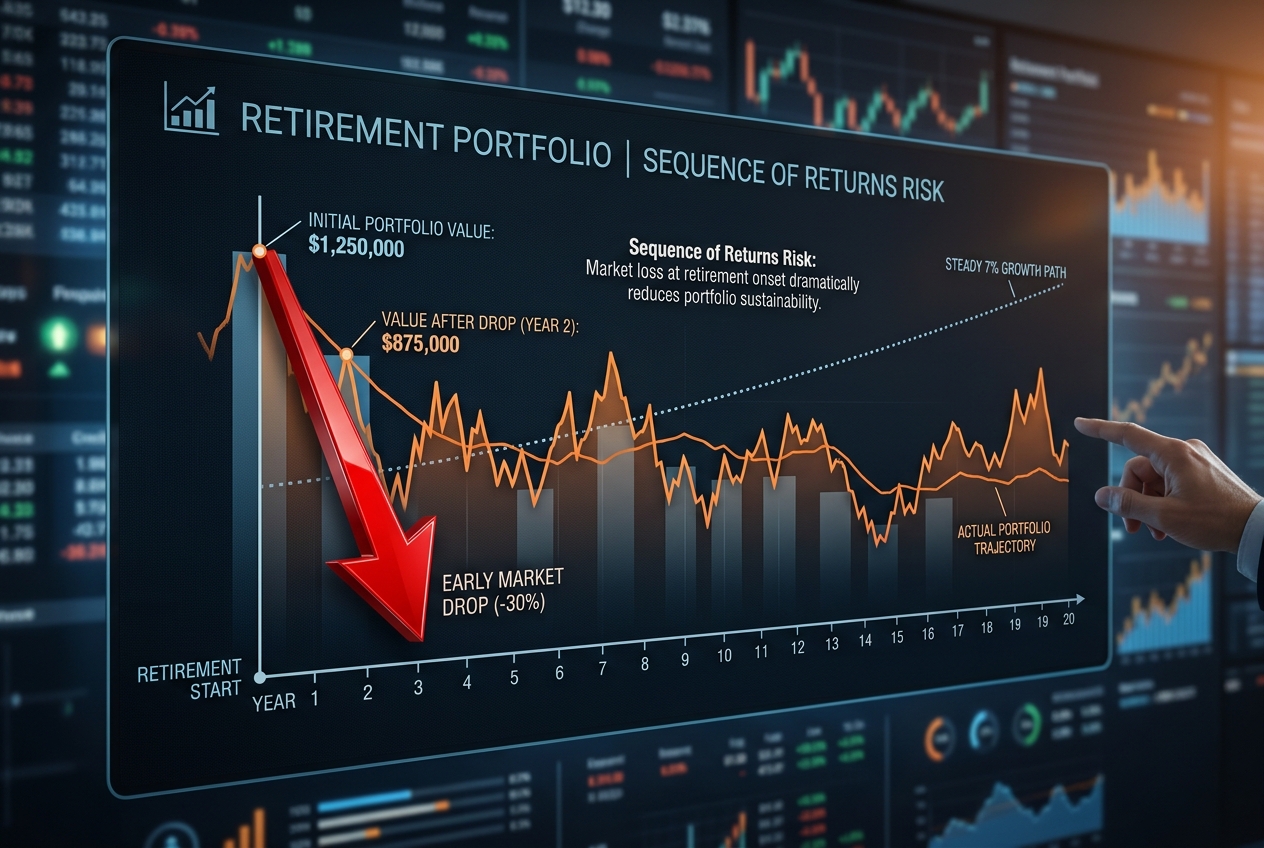
Imagine two retirees, both with $500,000 and both experiencing the exact same average market returns over 25 years. The difference? The *order* of those returns. If one retiree experiences strong market performance early on, followed by weaker years, their portfolio will likely last much longer than the retiree who experiences weak performance early, followed by strong years. When you're consistently withdrawing income from a portfolio that's simultaneously losing value, you're depleting your principal faster, leaving less to recover when the market eventually rebounds. This phenomenon is a major reason why 'is $500k enough to retire' is a complex question.
A $500,000 Portfolio Under Early Market Stress
Consider a scenario: You retire with $500,000 and plan to withdraw $1,667 per month. If the market drops 20% in your first year, your portfolio is suddenly worth $400,000. But you still need your $1,667 each month. So, you're withdrawing from a much smaller base, amplifying the impact of the loss. This forces you to sell more shares when prices are low. If that same 20% drop happened in year 15, after your portfolio has had time to grow and you’ve withdrawn less proportionally, the impact would be far less severe. For some households, this demonstrates a critical vulnerability of their retirement funds.
Mitigating the Impact of Bad Timing
Recognizing sequence of returns risk is paramount. Strategies to address it often involve creating a 'buffer' or 'income flooring' in the early years of retirement. This could mean having a few years of living expenses in more stable assets, or establishing guaranteed income streams that aren't subject to market fluctuations. The goal is to avoid selling growth-oriented assets during market downturns, giving them time to recover. This often leads to a different way of thinking about how your assets are allocated, prioritizing stability for early income needs while still allowing for long-term growth.
Related Articles
- Is $500K Enough to Retire? The Surprising Truth About Your Monthly Income
- The Silent Erosion: How Inflation Shrinks Your Retirement Income from $500K
- Beyond the 4% Rule: Why Your $500K Might Not Last Your Full Retirement
- Turn Savings Into Retirement Paycheck: Avoid Market Risk & Secure Income
- What Does $1 Million Really Produce in Retirement Income? The Reality
- How Inflation Quietly Destroys Retirement Income: What Retirees Need to Know
About the Author
John P. Sansaricq is a licensed insurance professional focused on retirement income planning, life insurance strategies, and educational resources for pre-retirees and retirees.
He helps individuals and families explore ways to protect savings, manage risk, and prepare for more informed retirement planning conversations.
See What This Looks Like For You
Reading about retirement strategies is helpful… but the real clarity comes from seeing how this applies to your own numbers.
This guide is designed to help you start thinking differently — the next step is simply understanding what your situation might actually look like.