In This Series
In This Guide
- The $500K Illusion: Why the Lump Sum Doesn't Tell the Full Story
- Decoding Your Monthly Income: What $500K Really Generates
- The Reality Check: Income vs. Real Retirement Expenses
- Hidden Risks That Threaten Your $500K Income Stream
- The Key Insight: Retirement is About Income, Not Just Savings
- Moving Forward: Understanding Your Own Retirement Income Picture
- In This Series
Key Takeaways
- A $500,000 nest egg typically generates around $1,667 in monthly income.
- This income often falls short when compared to actual retirement expenses, especially healthcare.
- Inflation, market downturns, and living longer can significantly erode a $500K portfolio.
- Retirement success is measured by sustainable income, not just the total savings amount.
- Understanding your income needs is the first step to bridging the gap between savings and lifestyle.
The $500K Illusion: Why the Lump Sum Doesn't Tell the Full Story
On paper, $500,000 looks impressive. It represents years of discipline and smart choices. But in retirement, this large sum transforms into a delicate balancing act. You’re no longer adding to it; you’re drawing from it. The focus shifts from growth to distribution, and that’s where the perception often clashes with reality. Many people assume a half-million dollars will cover all their needs, but they haven't translated that sum into a consistent, monthly paycheck. This is where many people are surprised by the actual purchasing power of their savings.
Decoding Your Monthly Income: What $500K Really Generates
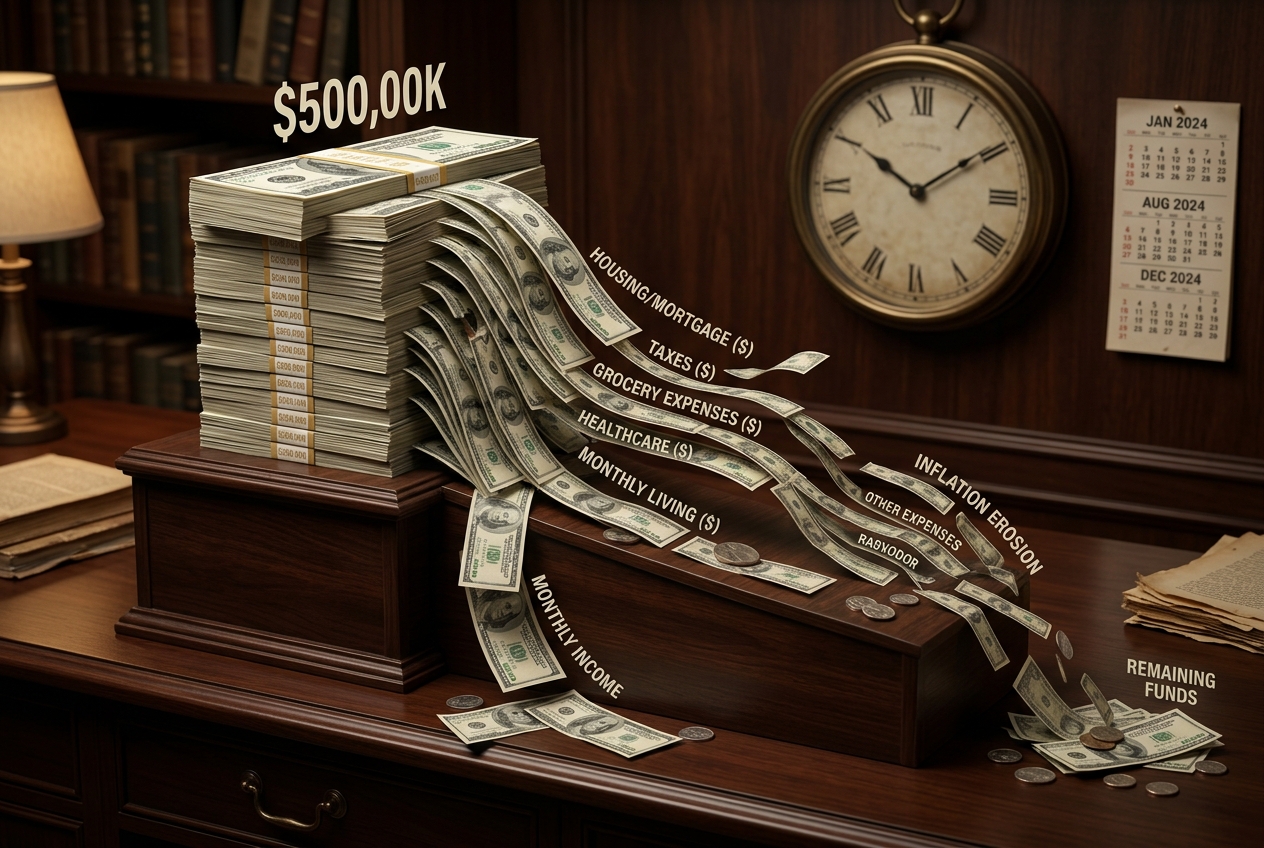
Let’s break down what $500,000 typically produces in terms of spendable income. A common guideline for sustainable withdrawals, often called the '4% rule,' suggests you can withdraw approximately 4% of your initial portfolio value in your first year of retirement, adjusting for inflation in subsequent years. So, if you have $500,000, 4% translates to $20,000 per year. Divide that by 12 months, and you're looking at **approximately $1,667 per month**. This is the practical, spendable income your $500,000 is designed to provide without significantly risking running out of money over a 25-30 year retirement. Does $1,667 per month sound like enough to cover your desired lifestyle?
The Reality Check: Income vs. Real Retirement Expenses
Now, let's compare that $1,667 per month to the actual cost of living in retirement. Consider your potential expenses: housing (mortgage or rent), property taxes, utilities, groceries, transportation, insurance, and perhaps most critically, healthcare. Medicare premiums, deductibles, and out-of-pocket costs can easily consume a significant portion of that income. For example, if your average monthly healthcare costs are $300, and your housing is $1,000, that’s already $1,300 gone, leaving only $367 for everything else. This is where many pre-retirees realize that 'is $500k enough to retire' needs a more nuanced answer. For some households, this stark comparison changes the conversation entirely, highlighting the gap between their savings and their monthly income needs.
The Key Insight: Retirement is About Income, Not Just Savings
This often leads to a different way of thinking about retirement. It's not about how much you have in your account balance on day one; it's about the consistent, reliable income that your assets can produce throughout your entire retirement. A $500,000 nest egg is a starting point, but its true value lies in its ability to fund your monthly life. This is where many people begin to question if their current savings strategy is truly optimized for income generation, or if it's simply focused on accumulation. Understanding this distinction is fundamental to building a retirement plan that offers true peace of mind.
Moving Forward: Understanding Your Own Retirement Income Picture
The goal isn't to scare you, but to provide clarity. Recognizing the difference between a lump sum and its actual monthly income potential is a powerful step. It allows you to realistically assess your financial situation and plan accordingly. This understanding often leads to exploring how your various assets—your $500,000, Social Security, and any other resources—can be strategically aligned to create a more predictable and resilient income stream. It’s about taking control and building a plan that truly supports the lifestyle you envision.
In This Series
Understanding the true value of your retirement savings is just one piece of the puzzle. In this series, we explore various aspects of turning your assets into reliable retirement income. You might find our articles on 'Retirement Income Strategies Beyond the 4% Rule' particularly insightful, or 'How Long Will Your Retirement Money Really Last?' to delve deeper into longevity planning. We also cover 'Navigating Market Volatility: Protecting Your Retirement Income' to address sequence of returns risk. Each article aims to provide a distinct perspective on securing your financial future.
Frequently Asked Questions
If I have $500,000, what monthly income can I realistically expect?
Using the common '4% rule' as a guideline, a $500,000 portfolio would generate an initial annual income of $20,000. This breaks down to approximately $1,667 per month. This amount would then typically be adjusted for inflation in subsequent years to maintain purchasing power.
What are the biggest expenses that could make $500,000 insufficient in retirement?
The most significant expenses that often surprise retirees include healthcare costs (Medicare premiums, deductibles, out-of-pocket expenses), housing (mortgage, rent, property taxes, maintenance), and the ongoing impact of inflation on everyday goods and services. These can quickly consume a large portion of a $1,667 monthly income.
How does Social Security impact whether $500,000 is enough to retire?
Social Security can significantly augment the income generated from your $500,000. If your Social Security benefit is, for example, $2,000 per month, combining that with the $1,667 from your savings brings your total monthly income to $3,667. This combined approach often makes a $500,000 nest egg feel more sufficient, as it's part of a broader income strategy.
What is 'sequence of returns risk' and how does it affect a $500,000 portfolio?
Sequence of returns risk refers to the danger that poor market performance early in your retirement can significantly deplete your portfolio, even if average returns over your entire retirement are good. If you're withdrawing from a $500,000 portfolio that experiences a downturn in its first few years, you're selling assets at a loss, leaving less to recover when the market rebounds, which can shorten how long your money lasts.
Related Articles in This Series
- The Silent Erosion: How Inflation Shrinks Your Retirement Income from $500K
- Timing is Everything: Why Early Market Drops Devastate a $500K Retirement Portfolio
- Beyond the 4% Rule: Why Your $500K Might Not Last Your Full Retirement
- When Should You Take Social Security? (62 vs 67 vs 70) — How to Compare Your Options
- Indexed Universal Life for Retirement Income: Beyond the Obvious
- IULs vs Fixed Indexed Annuities for retirement income: How to Compare the Two
About the Author
John P. Sansaricq is a licensed insurance professional focused on retirement income planning, life insurance strategies, and educational resources for pre-retirees and retirees.
He helps individuals and families explore ways to protect savings, manage risk, and prepare for more informed retirement planning conversations.
See What This Looks Like For You
Reading about retirement strategies is helpful… but the real clarity comes from seeing how this applies to your own numbers.
This guide is designed to help you start thinking differently — the next step is simply understanding what your situation might actually look like.