In This Series
In This Guide
- The Illusion of the Large Balance: Why Your 401(k) Isn't Just 'Money in the Bank'
- The Unseen Risks: Sequence of Returns and Income Erosion
- Beyond the 4% Rule: Designing an Income Strategy for Longevity
- Tax Traps and Opportunities: Maximizing Your Spendable Income
- The Behavioral Component: Shifting from Saver to Strategic Spender
Key Takeaways
- A large 401(k) balance doesn't automatically guarantee reliable retirement income.
- Sequence of returns risk can devastate your retirement income if not properly managed.
- Traditional withdrawal rules often fall short in providing long-term income stability.
- Tax efficiency is crucial for maximizing the net spendable income from your 401(k).
- Shifting from a saver's mindset to a strategic spender's mindset is vital for successful retirement income planning.
The Illusion of the Large Balance: Why Your 401(k) Isn't Just 'Money in the Bank'
A seven-figure 401(k) balance is certainly an achievement. Yet, it's crucial to understand that this number represents an asset, not an income stream. The shift from working and saving to living off your savings requires a profound change in how you view that money. While it might feel like 'money in the bank,' it's actually a pool of capital that needs to be strategically drawn down, managed through market cycles, and taxed appropriately to become reliable monthly income. This is where many people begin to question if their focus on the total balance has adequately prepared them for the complexities of converting it into spendable cash flow.
The Unseen Risks: Sequence of Returns and Income Erosion
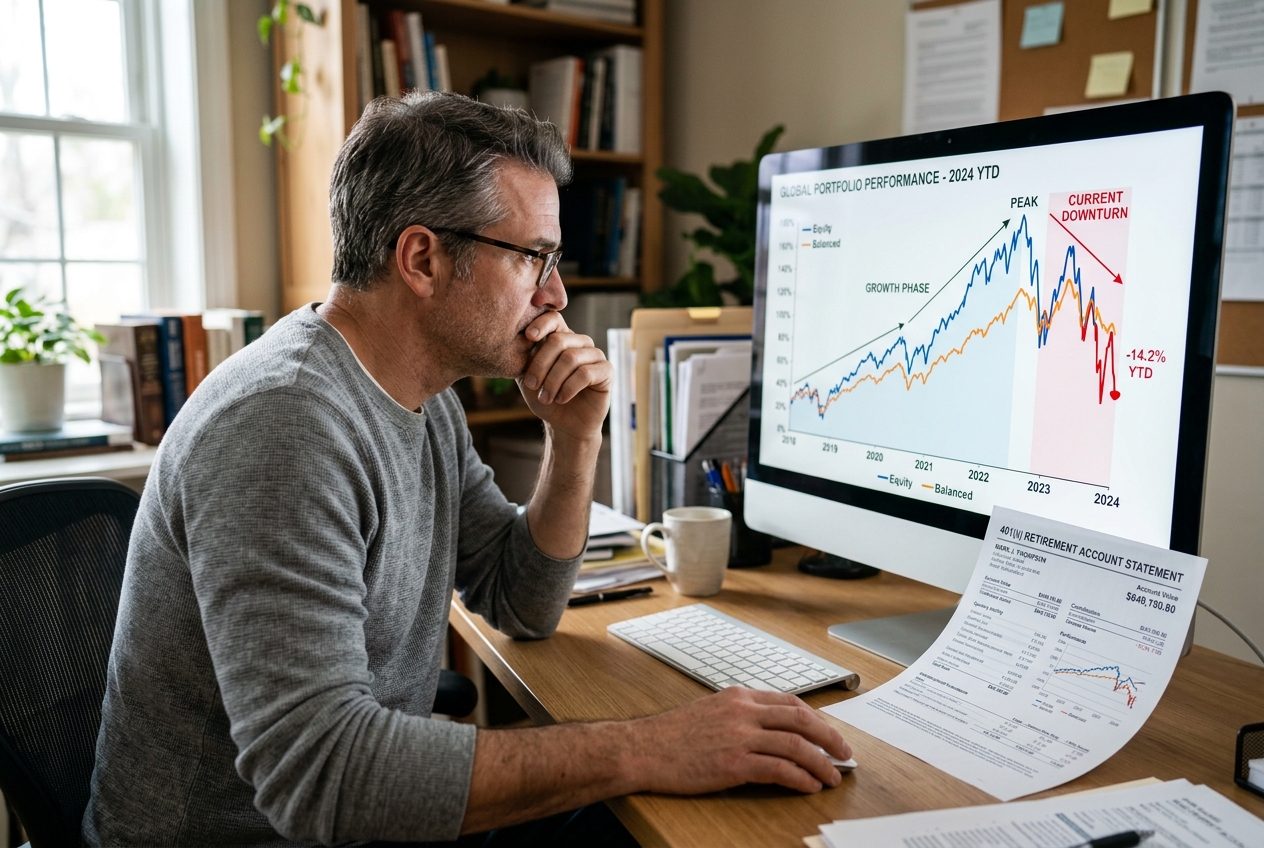
Most people don't realize that the order of investment returns, known as 'sequence of returns risk,' can be far more impactful in retirement than during your working years. Consider a household needing $5,000 per month from their $1,000,000 401(k). If the market drops 20% in their first year of retirement, they're now withdrawing from an $800,000 portfolio. Even if the market recovers later, those early withdrawals from a diminished balance mean less capital is left to grow, making it incredibly difficult to recover. This scenario often leads to a different way of thinking about how to protect your income stream from early market downturns, rather than just hoping for consistent growth.
Beyond the 4% Rule: Designing an Income Strategy for Longevity
The '4% rule' is a common guideline, suggesting you can withdraw 4% of your initial portfolio value each year, adjusted for inflation. While a useful starting point, it's not a guarantee, especially in today's environment of lower projected returns and longer lifespans. For some households, relying solely on this rule introduces too much uncertainty about income lasting 25-30 years. This often leads to exploring strategies that aim to provide a more predictable income floor, potentially by converting a portion of assets into a guaranteed income stream, or using approaches that participate in market growth while aiming to protect against significant losses, creating greater income stability throughout retirement.
Tax Traps and Opportunities: Maximizing Your Spendable Income
One of the most significant factors impacting your net retirement income from a 401(k) is taxes. Every dollar you withdraw from a traditional 401(k) is typically taxed as ordinary income. A seemingly healthy gross monthly income of $4,000 could shrink significantly after federal and state taxes. For example, a single retiree withdrawing $60,000 annually might owe $5,000-$10,000 or more in taxes, reducing their spendable income to $50,000-$55,000 annually. This is where many people begin to question how to strategically manage withdrawals, potentially utilizing Roth conversions in lower-income years or coordinating with other income sources, to keep more of their money working for them.
The Behavioral Component: Shifting from Saver to Strategic Spender
The psychological shift from accumulating wealth to spending it can be surprisingly challenging. Many people develop a lifetime habit of saving and watching their balances grow. In retirement, seeing that balance decrease, even according to a plan, can cause anxiety. This often leads to under-spending or making impulsive decisions during market downturns. For some, this changes the conversation from purely financial numbers to incorporating behavioral finance into their income plan, designing strategies that provide a sense of security and predictability, thereby reducing the emotional stress associated with drawing down their life savings.
Frequently Asked Questions
How much can I realistically expect to withdraw from my 401(k) each month in retirement?
The amount you can realistically withdraw depends on several factors, including your total balance, your age, your risk tolerance, other income sources, and current market conditions. While a 4% initial withdrawal rate is often cited, it's not a guarantee. For a $500,000 401(k), 4% is $20,000 per year, or about $1,667 per month before taxes. However, a personalized strategy considers your specific needs, longevity, and how to create a more stable income stream that aims to last your lifetime, rather than relying on a single rule.
Will my 401(k) last my entire retirement, especially if I live a long time?
Ensuring your 401(k) lasts your entire retirement, even with a longer lifespan, is a key challenge. Many people underestimate longevity risk. A 'set it and forget it' approach can leave you vulnerable. Strategies that convert a portion of your 401(k) into an income stream designed to last for life, alongside other diversified assets, are often explored to address this concern. This aims to provide a predictable income floor, reducing the worry of outliving your savings.
What happens to my 401(k) retirement income if the stock market drops significantly after I retire?
A significant market drop early in retirement can be very damaging due to 'sequence of returns risk.' If you're withdrawing income while your 401(k) balance is down, you're forced to sell more shares at a lower price, which accelerates depletion and makes it harder for your portfolio to recover. This is where strategic planning comes in, potentially involving strategies designed to provide downside protection or creating an income buffer from more stable assets to shield your essential income during volatile market periods.
Are there ways to make my 401(k) withdrawals more tax-efficient in retirement?
Yes, tax efficiency is crucial. Strategies include carefully timing your withdrawals to stay within lower tax brackets, considering Roth conversions in years with lower income, and coordinating your 401(k) distributions with other income sources like Social Security. Understanding how your withdrawals impact your overall taxable income and even Medicare premiums can help you keep more of your money, effectively increasing your net spendable retirement income.
Related Articles in This Series
- The Hidden Tax Drag on Your 401(k) Retirement Income
- Protecting Your 401(k) Income from Market Volatility in Retirement
- Why a 'Set It and Forget It' 401(k) Strategy Fails in Retirement
- Social Security Won't Be Enough: Bridge Your Retirement Income Gap
- The 401(k) Tax Trap Most Retirees Don’t See Coming — What It Is and How to Respond
- IULs vs Fixed Indexed Annuities for retirement income: How to Compare the Two
About the Author
John P. Sansaricq is a licensed insurance professional focused on retirement income planning, life insurance strategies, and educational resources for pre-retirees and retirees.
He helps individuals and families explore ways to protect savings, manage risk, and prepare for more informed retirement planning conversations.
See What This Looks Like For You
Reading about retirement strategies is helpful… but the real clarity comes from seeing how this applies to your own numbers.
This guide is designed to help you start thinking differently — the next step is simply understanding what your situation might actually look like.